Back
A Lender Just Walked. Could Your Desk Reroute by Monday?
By Robert Ward, Powersports Consultant, One Dealer Lane | Approximately 6-minute read
October 13, 2026
Share:
Your finance and insurance (F&I) manager has a nonprime buyer at the desk, and the lender that usually takes that deal just stopped taking new applications. Now someone has to re-key the credit app into another portal while a customer who already said yes waits.
That scenario got real for powersports dealers this fall. Merrick Bank told industry participants in a September 22 letter that it would stop originating powersports loans for all collateral types at the end of September 2026, Auto Finance News reported. On September 16, the Federal Reserve raised its target range for the federal funds rate by a quarter point, to 3.75 to 4 percent.
The direct answer
When a lender exits, a powersports dealer should be ready to move pending and future applications to another lender within one business day. Your exposure depends on two numbers: how much of your approval volume rode on that lender, and how long your desk takes to turn one declined powersports lender submission into a second one. With Merrick Bank out and OEM-branded finance programs multiplying, measure both now.
Key takeaways
Merrick Bank told industry participants in a September 22 letter that it would stop originating powersports loans for all collateral types at the end of September 2026, according to Auto Finance News.
BRP Financial Services went live August 24, 2026, and BRP told Auto Finance News that 90 percent of its dealer network signed up within two weeks.
Forest River Finance, powered by Octane, was set to launch October 1, 2026, as a manufacturer-backed RV finance program.
The Federal Reserve raised its target range by a quarter point to 3.75 to 4 percent on September 16, 2026, which can add rate pressure on approvals.
What changed in powersports lending this fall?
Lenders are reshuffling. In a September 25 exclusive, Auto Finance News reported that Merrick Bank will stop originating powersports loans for all collateral types, a change the outlet said could open room for other lenders, especially in nonprime.
At the same time, OEM-branded finance is growing. BRP Financial Services, powered by Octane, went live August 24, and BRP's chief financial officer told Auto Finance News that 90 percent of its dealer network signed up within two weeks. Forest River Finance was set to launch October 1. Octane says it has more than 4,000 dealer partners. Branded finance also stretches the customer lifecycle well past the sale, which gives dealers one more relationship to protect.
The volume at stake is large. Lenders reporting to the RV Industry Association's 2025 Survey of Lenders' Experiences made more than 220,000 retail indirect RV loans in 2025, totaling more than $10.4 billion funded.
Underwriting is changing too. Horsepower Financial, which leases motorcycles, off-road vehicles, and side-by-sides, told Auto Finance News, "We do not qualify with [FICO] score, but we have about 300 data points that we use." Each new program brings its own portal, credit appetite, and stips. You get more choice and more places for a deal to get stuck.
Why is lender concentration a desk problem, not just a finance problem?
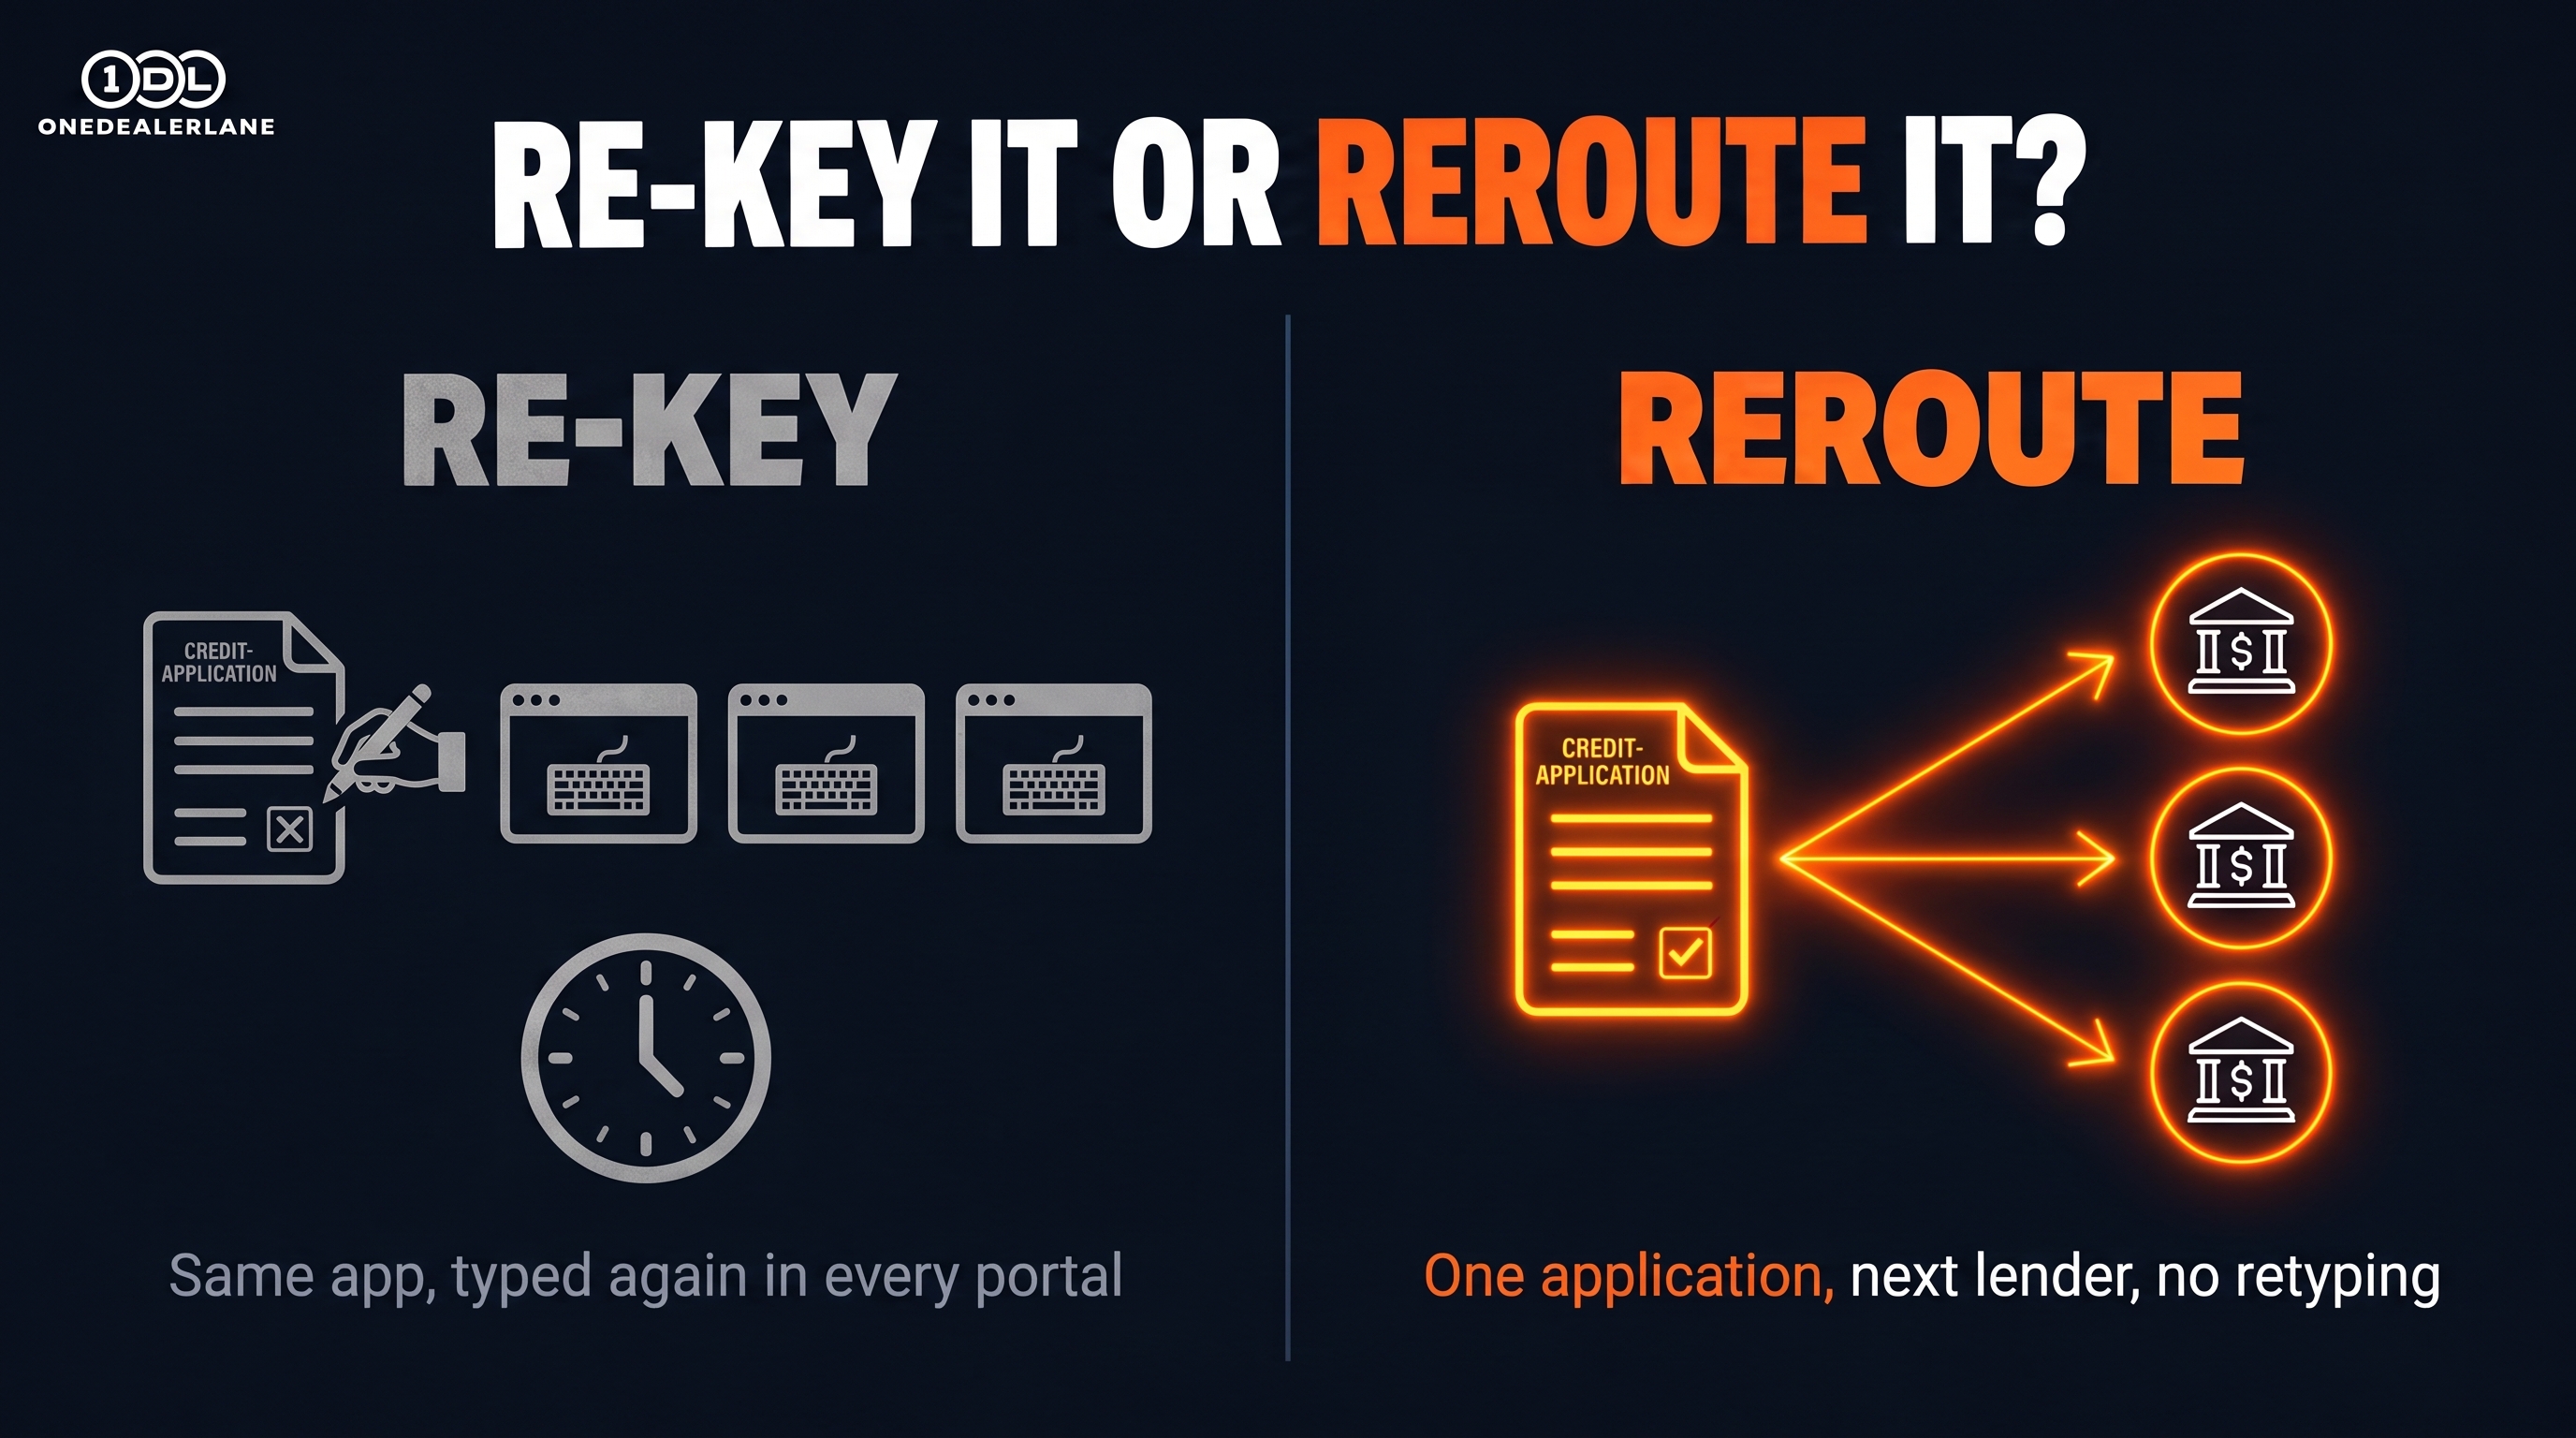
Concentration becomes a desk problem the moment a lender says no or goes away, because the next step is manual. Someone has to find a new home for the deal, re-key the credit application into another portal, and explain the delay to a customer who already said yes. Lenders have already automated the approval on their side; the re-keying happens in your store.
Most stores never measure this. They know their top lender by feel, not by approval share. If one lender carries most of your nonprime or older-unit deals, its exit hits the buyers who are hardest to place elsewhere.
Rates make it worse. After the Fed's September 16 increase, more deals can sit at the edge of approval. A desk that can resubmit in minutes keeps those buyers. A desk that re-keys every field risks losing them to the dealer down the road. Speed only helps when the file is solid, though. Lender capital can't fix a weak credit application, and a fast reroute still has to end in a sound deal structure.
How do you stress-test your lender mix?
Run these five checks on the last 90 days of credit applications. Each one takes an afternoon with a dealer management system (DMS) export and your F&I manager.
Check
How to measure it
Warning sign
Approval share by lender
Funded deals by lender, split by credit tier
One lender carries most of a tier
Time to reroute
Minutes from first decline to second submission
Longer than the customer will wait
Portal re-keying
Number of portals the team types the same app into
Every portal means a fresh re-key
Tier coverage
At least two active lenders per credit tier and unit type
A tier with only one active option
Program readiness
OEM-branded and new-lender enrollments completed
Programs your store has not enrolled in
Warning signs are editorial guidance, not industry benchmarks.
Read the results as a map of where one bad week could hurt you. If a single lender carries most of a tier, line up a second lender for that tier before you need it. If the reroute takes longer than a customer will sit in the F&I office, fix the process first: one clean application that can go to the next lender without being typed again.
What should you do this week?
- Pull 90 days of funded and declined deals and rank lenders by approval share in each credit tier.
- Time three reroutes, from first decline to the second lender's decision. Write the number down.
- List every lender portal your F&I team logs into and how many fields they retype in each.
- Confirm enrollment in every OEM-branded finance program for the brands you sell, including BRP Financial Services and Forest River Finance where they apply.
- Name a backup lender for each tier, and make sure the desk knows who it is before Monday.
Quick Lane, One Dealer Lane's digital credit application module, is built for the reroute moment. The customer completes one digital credit application on their own device or with your team. The store pulls soft or hard credit reports through 700Credit, with OFAC and Red Flags Rule checks in the credit workflow. The Quick Fill Extension (QFET) then populates lender forms, so the same application moves through multiple lender portals with less manual entry. Quick Lane is part of the ODL platform, which connects to the DMS and customer relationship management (CRM) system your store already runs.
Want to move a declined deal to your next lender without re-keying it? Fast track your lender submissions today.
Quick answers
What happens to deals when a powersports lender exits?
New applications to that lender stop, so any deal that depended on it has to be resubmitted elsewhere. For loans already funded, confirm servicing details with the lender directly. The immediate risk is pending deals and the credit tiers that lender covered.
How many lenders should a powersports dealer submit to?
There's no universal number. Every credit tier and unit type you sell should have at least two active lenders, so a single exit or decline never leaves a deal with nowhere to go.
Do OEM-branded finance programs replace third-party lenders?
No. Programs such as BRP Financial Services and Forest River Finance add options for their brands. Dealers still need third-party and credit union lenders for other brands, used units, and tiers a branded program won't cover.
What is a powersports lender submission?
A lender submission is the step where the dealer sends the customer's credit application and deal structure to a lender for a decision. Most stores submit through each lender's own portal, so a declined deal often means entering the same application again somewhere else.
How fast should a dealer reroute a declined deal?
Fast enough that the customer is still in the store. Time your own reroutes from first decline to second decision, and treat any reroute that outlasts the customer's patience as a process problem to fix.
About the author
Robert Ward is a Powersports Consultant at One Dealer Lane. He has spent his career in auto and powersports, from sales and F&I on the dealership floor to working with multiple software companies that serve the industry. Having sold every part of the deal from A to Z, he knows the process from first contact to funded deal. He has also trained dealer teams on sales and F&I processes, with proven success using the ODL platform.
Sources
- Auto Finance News, "Exclusive: Merrick Bank to Exit Powersports Lending" (September 25, 2026)
- BRP Inc., "BRP Announces the Launch of BRP Financial Services" (August 18, 2026)
- Auto Finance News, "BRP Financial Services Reaches 90% Dealer Enrollment after 2 Weeks" (September 3, 2026)
- PR Newswire and Octane, "Octane Partners with Forest River to Launch Forest River Finance Powered by Octane" (September 24, 2026)
- Auto Finance News, "Credit Data beyond FICO Gains Traction with Powersports Lenders" (September 24, 2026)
- Federal Reserve, "Federal Reserve Issues FOMC Statement" (September 16, 2026)
- RV Industry Association, Survey of Lenders' Experiences (2025 survey results)
Back to Top
Get more from every deal
Sign up for a free trial and start driving higher gross this month. No commitment, just results.
(877) 421-0135