Back
Confidence Hit 81.9. Is Your Desk Ready for the Payment Question?
By Josh Harnish, Customer Success Manager, One Dealer Lane | Approximately 5-minute read
October 12, 2026
Share:

The customer has picked the unit, pulled up a chair at the desk, and asked the first question on their mind: "What's my payment?" For powersports desking teams this fall, the first number the customer sees decides whether the conversation keeps going.
The pressure shows up in the data. The Conference Board's Consumer Confidence Index fell 6.7 points to 81.9 in September 2026, and 68.4 percent of consumers expect higher interest rates over the next 12 months. On September 16, the Federal Reserve raised its target range for the federal funds rate by a quarter point, to 3.75 to 4 percent.
The Direct Answer
Yes, your desk is ready if it shows every buyer two or three transparent payment options instead of one pencil. Q4 buyers walk in shopping a monthly payment. A desk that lays out the target unit, a lower-cost alternative, and a different structure side by side, each with term and total cost, gives the customer options to say yes to before anyone leaves to think about it.
Key Takeaways
The Conference Board's Consumer Confidence Index fell 6.7 points to 81.9 in September 2026, and 68.4 percent of consumers expect higher interest rates over the next 12 months.
The Federal Reserve raised its target range by a quarter point to 3.75 to 4 percent on September 16, 2026.
The University of Michigan's preliminary October 2026 consumer sentiment reading fell to 46.3, down from 48.1 in September.
A three-pencil desk shows the target unit, a lower-cost option, and a different structure, each with payment, term, down payment, and total cost.
Why Are Powersports Buyers More Payment-Sensitive This Fall?
Buyers are paying more to borrow and feel less sure about the economy. In its September 29 release, The Conference Board reported that the share of consumers expecting higher rates jumped 5.2 points to 68.4 percent, and plans to buy autos and homes edged down. The University of Michigan's preliminary October reading put consumer sentiment at 46.3, down from 48.1 in September and 13.6 percent below a year earlier.
Then the Fed raised rates on September 16, moving its target range to 3.75 to 4 percent.
Buyers are still coming in. What has changed is how fast one payment that's too high can end the conversation.
Where Does a Used Unit Fit on the Desk?
When the new-unit payment won't work, a used, prior-year, or lower-trim unit can keep the buyer in your store. That buyer may still buy today, just not the unit on the first pencil.
Pencil B works best when you choose the alternatives before the customer sits down. If one category is aging on the floor, a prior-year unit there can fill Pencil B and move inventory without discounting the whole showroom. On the used side, how you appraise trade-ins decides which units you'll have ready for the next payment-sensitive buyer.
What Goes Wrong When the Desk Shows One Pencil?
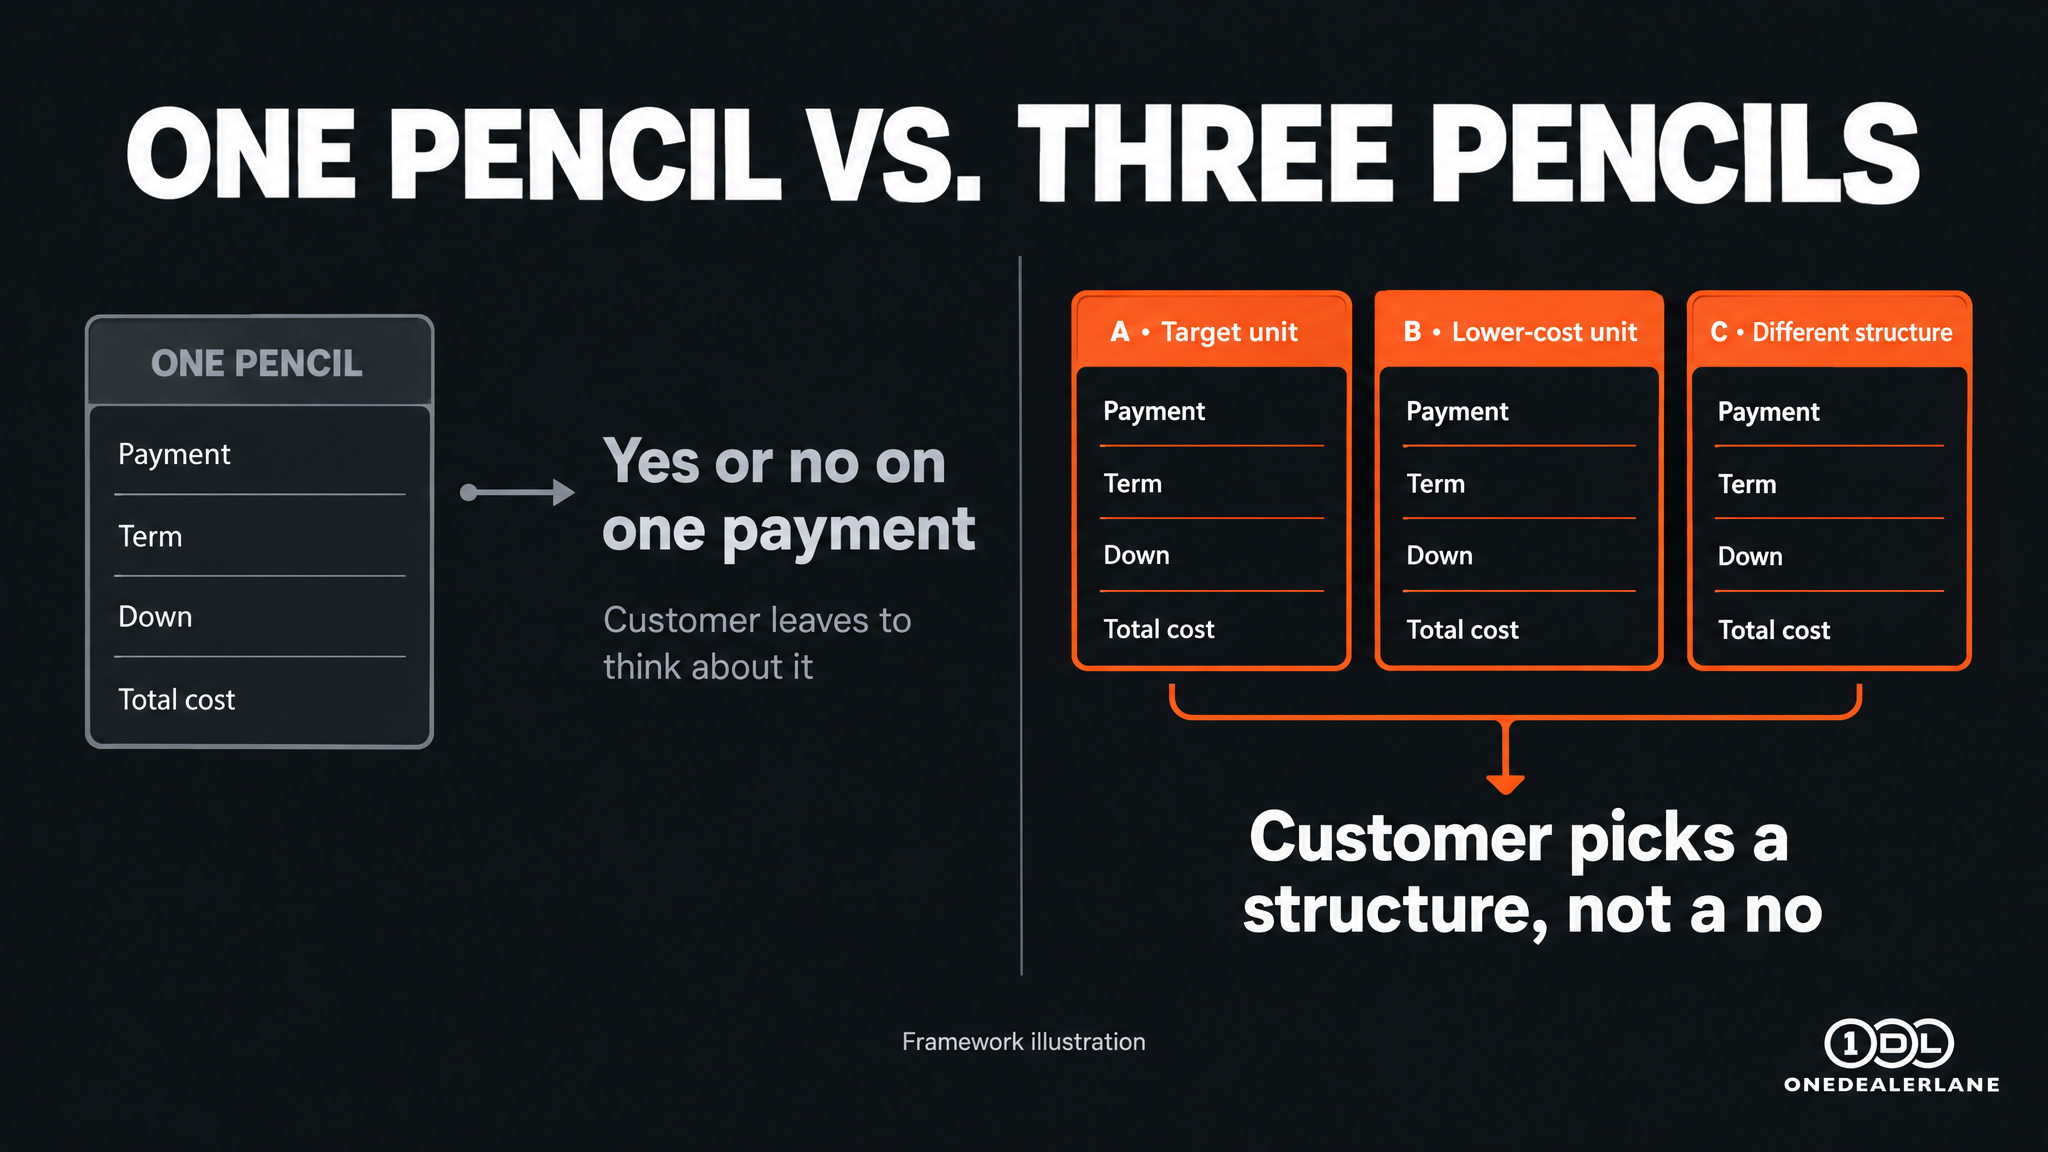
One pencil turns the conversation into a yes-or-no on a single payment. If the payment is too high, the customer leaves to think about it, and many don't come back.
The common fix, stretching the term until the payment fits, has a cost. In auto-industry data, Edmunds found that 29.6 percent of trade-ins toward new-vehicle purchases carried negative equity in the second quarter of 2026, and those buyers averaged $944 a month versus the $777 industry average. Powersports loans are not auto loans, but the risk works the same way: a long term can keep the deal alive today and leave your next trade-in customer owing more than the unit is worth. A lender approval on a stretched term doesn't make it a good deal for the customer.
What Does a Three-Pencil Powersports Desk Look Like?
Present all three options on one worksheet, at the same time, with the same level of detail.
Pencil
What it shows
Why it works
A. The target unit
The unit the customer picked, at a standard term and down payment
Respects the customer's first choice
B. The lower-cost option
A used, prior-year, or lower-trim alternative at the same term
Keeps the sale when A's payment is too high
C. The different structure
Unit A with more down or a shorter term, plus the total cost
Shows the trade-off between payment and total cost
Framework illustration. Show the total cost and term on every pencil, not just the payment.
If your lenders or OEM programs offer balloon payments, Pencil C is where that structure belongs, shown next to its total cost.
Three rules make it work. First, build all three pencils before the customer sees any of them, so no option looks like a retreat. Second, show the same facts on each: payment, term, down payment, and total cost. Consistent disclosure on every pencil can also help reduce your exposure to FTC pricing enforcement. Third, let the customer choose. A buyer who picks Pencil B has still bought from you, and a buyer who picks Pencil C has chosen a lower-cost loan knowing the trade-off. Either way, fewer customers leave to think about it.
What Should You Do This Week?
- Pull 30 days of unsold ups and note how many walked over payment.
- Pick one used or prior-year alternative for each of your top five new units.
- Set a desk rule: no single-pencil presentations. Every worksheet shows A, B, and C.
- Print total cost and term next to every payment, not just the monthly number.
- Put the trade value on the same worksheet so every pencil reflects it.
- Role-play the three-pencil conversation at Saturday's sales meeting.
Sales Lane, One Dealer Lane's digital desking tool, is built to show options. It supports multiple units on a deal, configurable tax and fee workflows, and customer-facing quote review, where the buyer can review payment options and select terms from a phone or tablet. ODL reports that dealers on the ODL platform save more than 30 minutes per deal, time your desk can spend on the conversation instead of the math.
Get a Platform Walkthrough
See how Sales Lane builds a three-pencil worksheet on your own deals. Call (877) 421-0135.
Quick Answers
What is desking at a powersports dealership?
Desking is the step where the sales manager structures the deal: unit price, trade value, down payment, term, rate, taxes, and fees. The desk then presents the payment to the customer. Digital desking moves that worksheet from paper into software that calculates each option.
Should dealers lead with the monthly payment?
Lead with options, not a single payment. Showing two or three payments side by side, each with term and total cost, keeps the conversation on choices the customer can say yes to.
How many payment options should the desk show?
Two or three. One option forces a yes-or-no answer, and three gives the customer a real choice without burying them in numbers.
Is stretching the loan term a good way to close more deals?
Only with care. Longer terms lower the payment but raise total cost and the chance of negative equity at trade-in. Show the total cost next to the payment so the customer can weigh the trade-off.
Do used units belong on a new-unit desk?
Yes, when the new-unit payment doesn't fit. A used or prior-year alternative at the same term can keep the customer in your store, and the customer still makes the choice.
About the Author
Josh Harnish is a Customer Success Manager at One Dealer Lane, with six years of dealership training experience and a decade of automotive retail leadership.
Sources
- The Conference Board, Consumer Confidence Survey release (September 29, 2026)
- Federal Reserve, "Federal Reserve Issues FOMC Statement" (September 16, 2026)
- University of Michigan, Surveys of Consumers (preliminary October 2026 results)
- Edmunds, "Q2 New-Vehicle Purchases with Negative Equity Trade-Ins Hit Record Monthly Payments and Interest Costs" (July 16, 2026; auto-industry data)
Back to Top
Get more from every deal
Sign up for a free trial and start driving higher gross this month. No commitment, just results.
(877) 421-0135